What Is A Debt-to-Income Ratio?
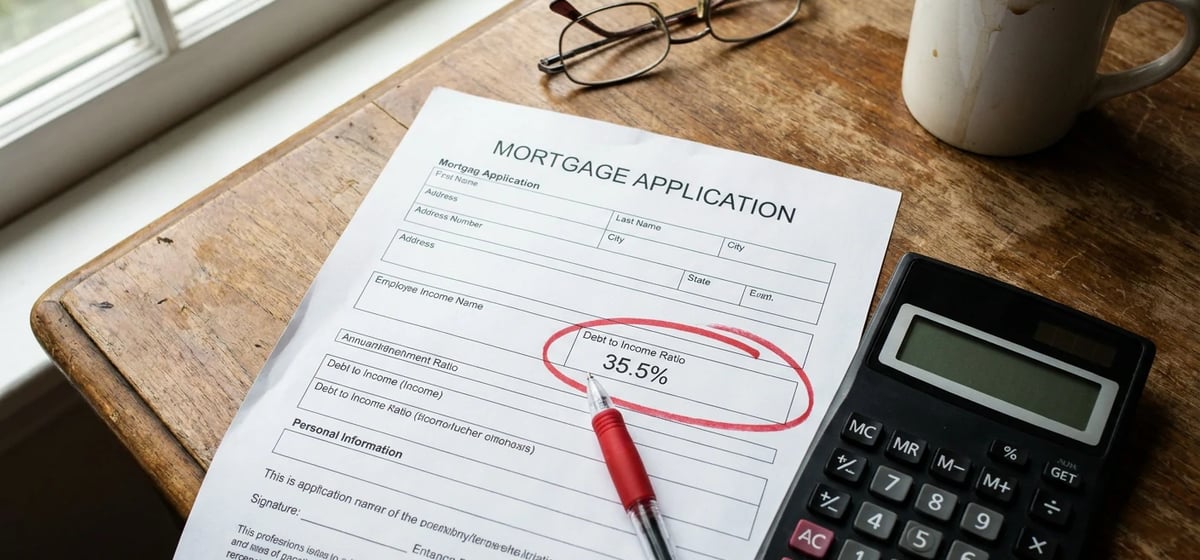
Your debt-to-income ratio is a simple percentage that compares your monthly debt payments to your monthly income. Lenders look at this number to decide if you can afford to take on a new mortgage. Banks developed this metric in the early 20th century to standardize lending and measure borrower risk. The phrase literally describes dividing your total liabilities by your total earnings.
To find this number, banks look at your gross monthly income. This is the money you make before taxes, health insurance, and retirement deductions come out of your paycheck. They divide your total monthly debt payments by that gross income figure. A lower percentage means you have plenty of money left over each month to pay for a house and handle unexpected repairs.
Why This Number Matters To You
When you start buying a home, banks want proof that you will not default on your loan. They use your debt-to-income ratio to measure exactly how tight your monthly budget is. If your ratio is too high, a bank will likely reject your loan application. They worry that one small emergency, like a broken furnace, could cause you to miss your mortgage payment.
Most lenders want to see a ratio below 43 percent, but lower is always better. If your ratio sits around 36 percent or less, banks usually view you as a very safe bet. You will likely get approved faster and receive better interest rates on mortgages. Keeping this number low gives you more financial breathing room to handle the real costs of homeownership.
What Counts As Monthly Debt
Not all of your monthly bills count toward this critical ratio. Lenders only care about fixed debt obligations that show up on your credit report. These typical debts include:
- Your rent or current mortgage payment.
- Monthly car loan or lease payments.
- Student loans and personal loans.
- Minimum monthly credit card payments.
Things like groceries, utility bills, and health insurance premiums do not count as debt. You also do not need to include cell phone bills, gym memberships, or streaming subscriptions. Lenders know you have to pay for these everyday living expenses, but they do not factor them into the strict debt-to-income math.
How To Lower Your Ratio
If your percentage is too high, you have two main ways to fix it before applying for a loan. You can either increase your monthly income or decrease your monthly debt. Paying off a car loan or wiping out a credit card balance drops your monthly debt payments. This instantly lowers your ratio and makes you look much better to potential lenders.
You must also avoid taking on new debt while you try to buy a house. Do not finance a new car or buy expensive furniture on credit until after you close on your home. A sudden jump in your monthly debt payments can completely ruin your ratio. This common mistake can cause your lender to cancel your mortgage at the last minute.