What is a windstorm deductible?
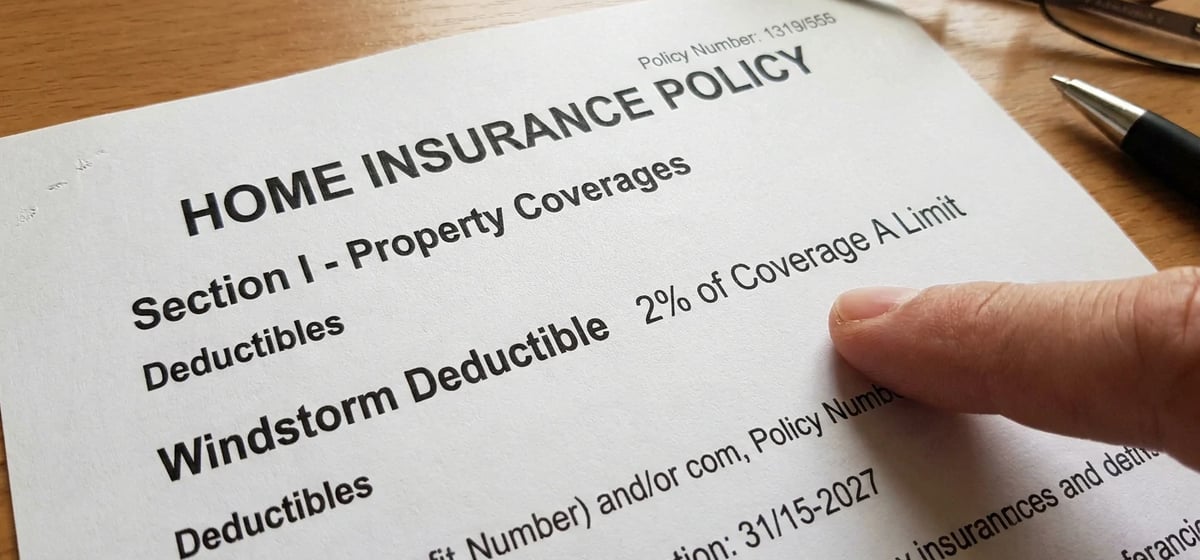
A windstorm deductible is the amount of money you must pay out of pocket before your insurance covers wind damage. You will usually see this as a percentage of your total home value rather than a flat dollar amount. It applies when a named storm or high winds damage your home.
Insurance companies adopted this term in the late twentieth century to limit their massive losses from hurricanes. The word deductible comes from the Latin word deducere. That means to lead away or subtract.
Standard home insurance deductibles are usually a flat fee like $1,000 or $2,000. A windstorm deductible works differently. It is tied to your dwelling coverage limit. This means your out of pocket cost can be much higher than a normal claim.
How the math works
You will typically see windstorm deductibles set between 1 percent and 5 percent of your dwelling coverage. Your dwelling coverage is the total amount your house is insured for. It is not the market value or the price you paid for the home.
Let us look at a quick example. Imagine your home is insured for $300,000 and you have a 2 percent windstorm deductible. If a storm tears off your shingles, you are responsible for the first $6,000 of the repair costs.
You do not usually write a check to your insurance company for this amount. Instead, they subtract your deductible from the final payout. If the total roof repair costs $15,000, your insurance company will send you a check for $9,000.
Replacing a roof completely usually costs $8,000 to $15,000, though ranges vary based on your location and materials. If your damage is minor, the repair cost might not even reach your deductible amount. In that case, insurance pays nothing.
When does it apply?
Insurance companies use specific triggers to decide when this deductible kicks in. The rules vary by state and by the insurance provider. Your policy will state exactly what event activates the higher deductible.
Common triggers for a windstorm deductible include:
- A storm named by the National Weather Service.
- A hurricane reaching category one status or higher.
- Winds recorded above a specific mile per hour threshold.
If a random summer thunderstorm blows a branch onto your house, your standard flat deductible usually applies. But if a named tropical storm rolls through, the higher windstorm deductible takes over. This is a crucial detail to check in your Home Insurance policy.
What to watch for
Many homeowners do not realize they have a separate deductible for wind until a storm hits. You can find this information on the declarations page of your insurance policy. Look for a section labeled wind, hail, or named storm.
If you upgrade your home to resist wind, you might be able to lower this cost. Some states require insurance companies to offer discounts if you install hurricane shutters or special roof clips. Upgrading your Roofing materials can sometimes reduce your premium.
Keep in mind that federal home energy tax credits ended completely on December 31, 2025. You cannot claim these federal credits for impact windows or doors in 2026 or later, though work completed in 2025 can still be claimed on your 2025 tax return. For incentives today, check with your utility and state energy office for local rebates or free energy audits.